What Do the Latest Suburban Chicago Vacancy Numbers Show?
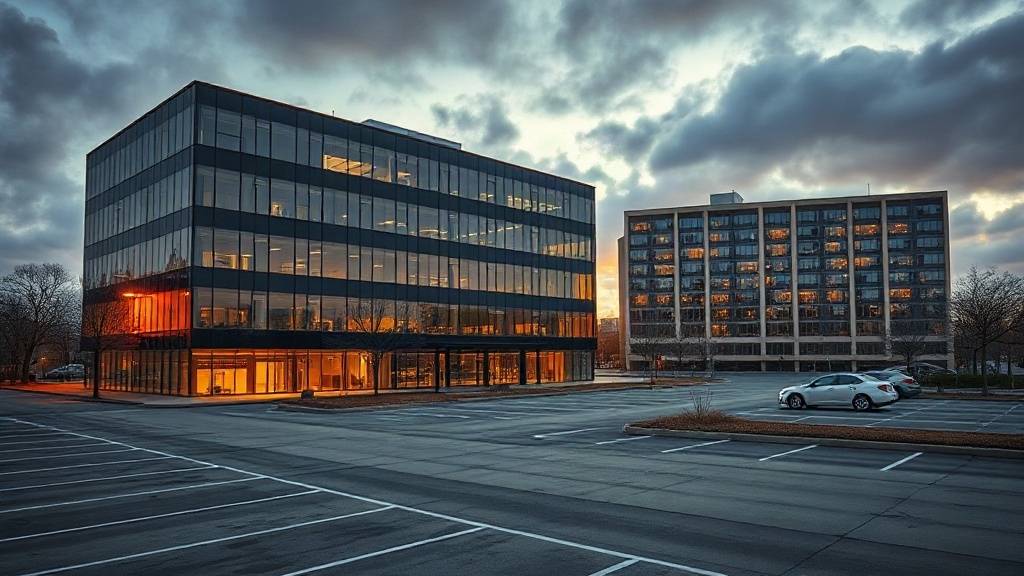
Suburban Chicago office vacancy is showing signs of stabilization, but the market remains under heavy pressure.
Quarterly Readings Show a Pause
Recent quarterly readings indicate that vacancy has flattened in some reports. One measure held at 33.1% for a second consecutive quarter, ending a 21-quarter run of increases.
CBRE recorded direct vacancy at 28.2% in Q2 2026, slightly below the 28.4% reported in Q1. Another midyear reading showed direct vacancy easing to 25.5% from 26.0% at year-end 2025.
Vacancy Measures Remain Elevated
The figures are not directly interchangeable: reports use different vacancy measures and coverage. One placed overall vacancy at 24.2% in Q2 2026, 230 basis points higher year over year.
Despite small quarterly improvements in some readings, elevated levels and year-over-year increases show that stabilization has not yet become a broad recovery. Submarket results also vary, with inner areas generally outperforming weaker Northwest suburbs. Nationally, office vacancy averaged 18.6%, underscoring the pressure facing markets with higher rates. In Q3 2026, suburban office vacancy rose 180 basis points year over year to 24.1%.
Why Has Suburban Chicago Office Vacancy Stabilized?
Vacancy has stopped climbing as the suburban Chicago office market adjusts to weaker demand through shrinking inventory and a steadier, lower level of leasing activity.
The office footprint has fallen from nearly 100 million square feet in 2020 to 93.2 million, limiting the space available to remain vacant.
This supply-demand rebalancing, rather than a leasing surge, has helped stabilize the rate.
Leasing volume remains below pre-pandemic levels, but activity has settled into a more predictable baseline.
First-quarter volume of just over 1.1 million square feet reflects that lower operating level.
Workplace downsizing continues, though companies appear to be shedding space more measuredly, reducing the likelihood of sudden vacancy increases.
Flight to quality leasing is concentrating interest in strong, well-located buildings.
Measured corporate returns, including renewal decisions by large tenants, have also supported a steadier market tone, despite continued caution and fewer major deals.
Denver’s industrial market offers a contrasting example, with vacancy reaching 8.4% in Q2 2025 amid excess logistics supply from the recent development boom.
How Are Office Conversions Cutting Suburban Supply?
Since 2020, conversions and redevelopment have removed roughly 7.3 million square feet of suburban Chicago office space, reducing inventory as weak leasing demand persists.
Nearly 6 million square feet has reportedly gone offline over five years, bringing total inventory below 95 million square feet for the first time since 2007.
Older Offices Face Removal
Developers are targeting underused campuses and dated Class B and C buildings for conversion to housing, industrial, retail, and data center uses.
Properties with transportation access can be particularly suitable for new uses, while large campus layouts often no longer match tenant needs.
These office conversion trends are reshaping the supply base.
More Reductions Are Planned
Of 13.6 million square feet traded since 2020, about 6.3 million has been removed for redevelopment.
Another 2.2 million square feet is slated for demolition or redevelopment, and further projects remain in the redevelopment pipeline.
Taking vacant offices offline helps cushion vacancy measures, though sustained improvement also depends on stronger leasing demand.
Where Is Suburban Chicago Vacancy Highest and Lowest?
The removal of older offices is reshaping suburban Chicago’s supply, but vacancy remains sharply uneven by location.
In the first half of 2026, the Northwest Suburbs recorded the highest direct vacancy, at 31.5%, about six percentage points above the suburban average.
Its rate was also highest in Colliers’ first-quarter tracking, at 32.5%. A separate Transwestern measure placed overall vacancy there at 27.8%, reflecting differences in reporting.
The Northern Suburbs ranked second-highest for direct vacancy, at 26.9%.
By contrast, the East/West Corridor had the lowest direct rate, at 21.4%, while O’Hare followed at 23.9%.
Oak Brook also remained among the lower-vacancy areas, recording 23.2% in Colliers’ first-quarter comparison. Near North posted 18.0% in an inner-suburban grouping.
The gap highlights distinct local market conditions.
Why Isn’t Stabilization an Office Market Recovery?
A pause in rising vacancy does not signal recovery for suburban Chicago’s office market.
Vacancy remained 33.1% in late 2026, compared with about 24% before the pandemic.
Direct vacancy stayed in the mid-20% to high-20% range.
Shrinking supply masks weak demand
Office conversions to industrial or residential use have reduced available inventory.
That can steady vacancy even when occupied space is not expanding meaningfully.
Net absorption remained volatile and often negative, including a reported 1.3 million-square-foot decline through mid-2026.
Gains remain uneven
Leasing exceeded 2 million square feet in the first half of 2026 in one report, but larger tenants continued to give back space.
Positive absorption in Q2 was followed by a negative Q3 result.
Isolated gains do not establish durable demand or sustained occupancy growth.
Asking rents largely stabilized, but broad rent growth and stronger absorption remain necessary signs of recovery.
Assessment
Suburban Chicago’s office vacancy rate has stopped climbing, but the plateau reflects a smaller supply base as well as steadier demand. Conversions are removing some underused buildings, while vacancies remain uneven across local markets.
The halt in rising vacancy offers a sign of stabilization, not proof of recovery. Leasing strength, sustained occupancy gains, and reduced available space will determine whether the market can move beyond its current pause.